How Tokenized Deposits Differ From Stablecoins
The line between traditional money and crypto-native assets is blurring fast, and nowhere is that more visible than in the debate over tokenized deposits versus stablecoins. Both aim to move value on blockchains with low friction and high speed, yet they sit in very different legal, regulatory, and business worlds. Understanding those differences is now critical for banks, fintech founders, institutional investors, and policymakers trying to build or regulate the next generation of digital finance.
What Each Term Actually Means
At first glance, tokenized deposits and stablecoins can look similar: both are digital tokens on a ledger that are meant to maintain a stable value, often pegged to a fiat currency like the US dollar or euro. Under the hood, however, they represent different legal claims and risk profiles.
Tokenized deposits are on-chain representations of bank deposits. A customer places money with a licensed bank; instead of (or in addition to) seeing a line item in online banking, they receive a token on a distributed ledger that evidences their deposit claim on that bank. Economically and legally, this is still a deposit: it sits on the bank's balance sheet, may be covered by deposit insurance where applicable, and is subject to full banking regulation. The token is essentially a new wrapper around a familiar liability.
Stablecoins, by contrast, are blockchain-based tokens that aim to maintain a stable value relative to a reference asset, most commonly a fiat currency. But they are not, by default, bank deposits. Most leading stablecoins are issued by non-bank entities that hold reserves (cash, short-term government securities, other assets) to back the tokens in circulation. Holders have a claim on those reserves under the terms set by the issuer, but they are usually not protected by deposit insurance or prudential banking rules. Even when a stablecoin is issued by a bank, it is typically structured as a distinct instrument with its own legal treatment.
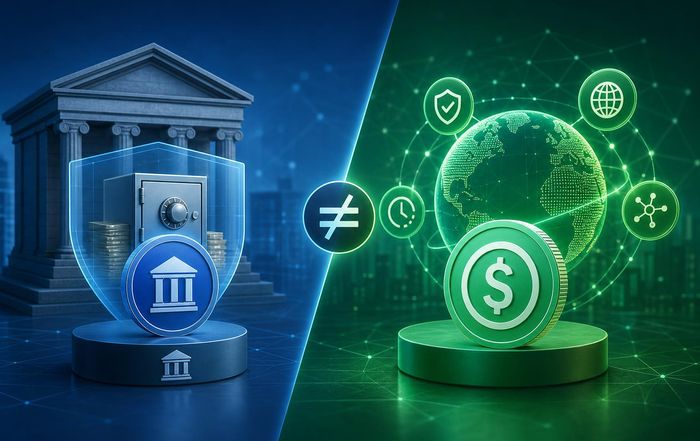
This basic distinction-deposit claim on a regulated bank versus claim on a reserve pool held by a non-bank or special-purpose vehicle-drives most of the practical differences that follow.
Legal Nature: Claims, Creditors, and Balance Sheets
The legal character of a tokenized deposit is relatively clear in jurisdictions with mature banking law. It is a standard bank deposit, just with tokenized bookkeeping. The customer becomes a creditor of the bank, and the bank records a matching liability on its balance sheet. In many countries, such deposits benefit from statutory protection such as FDIC insurance in the United States or schemes overseen by the European Banking Authority in the EU. The token does not change that underlying legal reality; it merely changes how ownership is recorded and transferred.
Stablecoins occupy a more fragmented legal landscape. A fiat-backed stablecoin like USDC or USDT is generally a claim on the issuing company or trust, not a deposit in the banking sense. The reserves may be held with multiple banks, in government bills, or other short-term instruments, and the rights of token holders are defined by the issuer's terms of service and applicable securities, payments, or e-money laws. In some jurisdictions, regulators such as the Financial Conduct Authority in the UK or under the EU's MiCA framework treat certain stablecoins as e-money or "asset-referenced tokens," imposing specific requirements but still not equating them with insured deposits.
This difference in legal status matters most in stress scenarios. If a bank that issued tokenized deposits fails, deposit guarantee schemes and bank resolution frameworks apply. If a non-bank stablecoin issuer fails, token holders stand in line with other creditors, and their recovery depends on how reserves were managed, segregated, and prioritized. Even where regulators push for high-quality reserves, the legal path to recovery is often slower and more uncertain than for insured deposits.
Regulatory Perimeter: Banking Rules vs. New Regimes
Because tokenized deposits are simply deposits in digital form, they sit squarely inside existing banking regulation. They are governed by capital and liquidity rules such as Basel III standards, anti-money laundering (AML) and know-your-customer (KYC) requirements, and local supervisory expectations on operational resilience, cyber security, and data protection. Central banks and prudential supervisors-such as the Bank for International Settlements community of regulators-tend to see tokenized deposits as an evolutionary technology change rather than a new type of money.
Stablecoins, on the other hand, have forced regulators to build new categories. In the United States, agencies including the Federal Reserve, SEC, and CFTC have each weighed in on aspects of stablecoin activity, but there is still no single, comprehensive federal regime dedicated solely to stablecoins. In the EU, the Markets in Crypto-Assets (MiCA) regulation explicitly defines rules for e-money tokens and asset-referenced tokens, covering governance, reserve quality, redemption rights, and disclosures. In Asia, jurisdictions like Singapore through the Monetary Authority of Singapore and Hong Kong through the HKMA have published detailed frameworks for fiat-referenced stablecoins, often focusing on licensing issuers and ensuring robust reserve management.
The net result is that tokenized deposits inherit the well-understood regulatory environment of banking, while stablecoins sit in a patchwork of new or evolving regimes that vary by jurisdiction. For global fintechs and banks, that divergence affects where and how they can launch products, what licenses they need, and how cross-border use will be treated.
For readers interested in how this regulatory context intersects with broader fintech and banking developments, related coverage on fintech innovation and banking transformation provides additional background.
Reserve Models and Risk Profiles
Behind the legal and regulatory differences lie distinct economic risk models. Tokenized deposits use the traditional fractional-reserve banking model: the bank takes deposits (now tokenized), lends or invests a portion, and keeps sufficient capital and liquidity buffers to meet withdrawals and regulatory standards. The depositor is exposed to the credit risk of the bank, mitigated by capital requirements and, for smaller balances, by deposit insurance where available.
Stablecoins, at least in their fiat-backed form, typically aim for something closer to a "full reserve" model. Issuers promise that each token is backed one-to-one by high-quality liquid assets such as cash and short-dated government securities. Leading issuers publish attestations or audits by firms like Deloitte or Grant Thornton, and some are subject to oversight by bodies like the New York Department of Financial Services. However, history shows that practices have not always matched marketing claims; questions about reserve quality and transparency have periodically emerged in relation to several major stablecoins.
Algorithmic stablecoins represent a different and riskier design, relying on market incentives and smart-contract mechanisms rather than explicit reserves. The collapse of TerraUSD in 2022 demonstrated how quickly such systems can unravel when market confidence breaks. Tokenized deposits, by design, avoid that category of risk: their value is not maintained by arbitrage mechanisms or algorithmic supply adjustments but by the underlying bank's ability to honor withdrawals at par.
From a user's perspective, the trade-off is between bank credit risk (mitigated by regulation) and reserve management risk (mitigated by issuer practices and emerging rules). For institutional treasurers, asset managers, and corporate users, this difference can shape whether a token is treated as cash-equivalent, a money-market-like instrument, or a more speculative asset.
Settlement, Infrastructure, and Interoperability
Both tokenized deposits and stablecoins aim to improve how money moves, but they tend to live on different types of infrastructure.
Tokenized deposits are often issued on permissioned or consortium blockchains, or even on tokenized ledgers that are not fully public. Large banks and market infrastructures have experimented with private networks using technologies like R3 Corda, Hyperledger Fabric, or permissioned variants of Ethereum. These environments allow banks to maintain strict control over who can hold tokens, how transfers occur, and how compliance checks are integrated. They also integrate more readily with existing core banking systems and regulatory reporting tools.
Stablecoins have grown up mainly on public blockchains such as Ethereum, Solana, and Tron, where open participation and composability with decentralized finance (DeFi) protocols are key attractions. This openness enables use cases like automated market making, on-chain lending, and global peer-to-peer transfers without intermediaries. However, it also raises challenges for traditional compliance, sanctions enforcement, and transaction monitoring, prompting regulators and organizations like FATF to issue guidance on virtual asset providers and travel rule obligations.
In practice, this means tokenized deposits are currently more aligned with institutional and wholesale use cases-interbank settlement, tokenized securities payments, and corporate cash management-often in controlled environments. Stablecoins, by contrast, have achieved broad retail and cross-border usage, especially in emerging markets where access to stable foreign currency and digital payment rails is limited. For readers focused on the intersection of crypto and mainstream finance, our crypto coverage and stock-exchange sections explore how these infrastructures are converging with capital markets.
Use Cases: Who Uses What, and Why
The choice between tokenized deposits and stablecoins is not merely technical; it reflects different user needs and risk appetites.
Large banks and market infrastructures see tokenized deposits as a way to modernize existing payment and settlement processes without stepping outside the banking perimeter. Projects in Europe, North America, and Asia are exploring tokenized commercial bank money to support delivery-versus-payment for tokenized bonds and equities, intraday liquidity management, and programmable corporate cash flows. Because the tokens remain deposits, treasurers can treat them as familiar cash holdings, easing accounting and risk management.
Stablecoins have so far dominated in areas where bank-led infrastructure has been slow or inaccessible. Cross-border remittances, crypto trading, DeFi lending, and on-chain derivatives all rely heavily on stablecoins as collateral and settlement assets. In some countries with high inflation or capital controls, dollar-pegged stablecoins function as a de facto savings instrument for individuals and small businesses. Fintech startups use stablecoins to build global payment products, payroll services for remote workers, and on/off-ramp solutions between fiat and digital asset ecosystems.
There is also a growing middle ground. Some licensed banks and fintechs are exploring "bank-issued stablecoins" or tokenized money market funds, blurring the line between deposit tokens and stablecoins. Regulatory initiatives, including discussions at the International Monetary Fund and Financial Stability Board, are pushing for clearer categorization of these instruments, especially when they reach systemic scale.
Readers interested in how these use cases intersect with entrepreneurship and employment can find additional context in our founders and jobs sections, which track how new digital money models are reshaping fintech careers and startup opportunities.
Compliance, KYC, and Privacy
Compliance architecture is another major differentiator. Tokenized deposits are typically issued only to customers who have passed full KYC and onboarding with a bank or licensed institution. Transfers often occur within a closed user group or under rules that enforce identity checks at each hop. This design aligns with AML expectations from bodies like FATF and national regulators, but it limits open composability with permissionless DeFi protocols.
Stablecoins, especially on public chains, enable peer-to-peer transfers between pseudonymous addresses. While regulated exchanges and custodians perform KYC on their users, tokens can circulate outside these gateways. Blockchain analytics firms such as Chainalysis or Elliptic help regulators and compliance teams trace flows and identify suspicious patterns, but there is still more scope for unregulated or lightly regulated activity than in traditional banking.
Privacy sits at the intersection of these concerns. Tokenized deposits on permissioned networks may offer more controlled data sharing, with access limited to relevant counterparties and supervisors. Public-chain stablecoins, by contrast, are transparent at the transaction level but pseudonymous at the identity level, creating a different mix of privacy and traceability. Emerging technologies like zero-knowledge proofs and "compliant DeFi" frameworks could narrow this gap over time, but today the privacy-compliance balance remains a key design choice for institutions deciding which model to adopt.
For a bigger view on how these compliance questions fit into digital finance, people can find our content on security and AI in financial regulation, where algorithmic monitoring and risk scoring are increasingly central.
Interaction With Central Bank Digital Currencies
Any discussion of tokenized deposits and stablecoins now intersects with central bank digital currencies (CBDCs). Dozens of central banks, coordinated in part through the Bank for International Settlements, are experimenting with retail and wholesale CBDCs as new forms of digital central bank money. This raises questions about how private tokens will coexist with public-sector money.
Tokenized deposits are often positioned as complementary to CBDCs, especially in wholesale contexts. In many design blueprints, wholesale CBDCs would be used for settlement between banks and central banks, while tokenized deposits remain the primary instrument for customers. Banks could move liquidity between CBDC and tokenized deposits to optimize settlement and intraday funding, preserving the two-tier banking system that institutions like the European Central Bank and Federal Reserve frequently emphasize.
Stablecoins are more of a wildcard. Some policymakers see them as useful private-sector innovation that can coexist with CBDCs, especially if issued under strict regulatory regimes. Others worry that large global stablecoins could undermine monetary sovereignty or complicate monetary policy transmission, especially in smaller economies. International organizations such as the IMF and World Bank have highlighted both the potential for financial inclusion and the risks of currency substitution when dollar- or euro-linked stablecoins circulate widely in emerging markets.
How this triangle-CBDCs, tokenized deposits, and stablecoins-evolves will shape the long-term structure of digital money. For folks watching the macroeconomic and policy dimensions, our economy and world sections regularly cover central bank experiments and cross-border payment reforms.
Strategic Choices for Banks, Fintechs, and Policymakers
For banks, the strategic question is whether to focus on tokenized deposits, issue their own stablecoins, partner with existing stablecoin issuers, or pursue some combination. Tokenized deposits align best with current regulation and risk management, but may lack the open-network reach and developer ecosystem that public-chain stablecoins enjoy. Bank-issued stablecoins on public networks could offer a bridge, but they must navigate complex regulatory classification and interoperability questions.
Fintech startups and DeFi protocols must decide which forms of digital money to support. Stablecoins currently dominate DeFi collateral and liquidity pools, but tokenized deposits could gain traction if banks make them accessible on interoperable networks or via APIs. Startups building payment, remittance, or treasury tools must weigh customer trust, regulatory exposure, and integration complexity when choosing their base asset.
Policymakers and regulators, meanwhile, face the task of creating frameworks that preserve financial stability while allowing innovation. International coordination, through bodies like the FSB, IMF, and BIS, is increasingly important as tokens cross borders in seconds while regulation remains national. Questions about consumer protection, resolution of failed issuers, data governance, and interoperability between different token types are moving from theory to practice.
For visitors interested in how these choices intersect with broader business models and sustainability, our business and environment sections examine how digital money infrastructure affects everything from corporate strategy to the energy footprint of financial systems.
Where the Distinction Matters Most
The headline difference between tokenized deposits and stablecoins-deposit claim versus reserve-backed token-can sound abstract, but it has concrete implications:
In a bank failure, tokenized deposit holders are treated like other depositors, often with insurance up to certain limits; stablecoin holders rely on issuer-specific arrangements and local law.
For regulatory capital, liquidity, and reporting, tokenized deposits fit into existing banking frameworks; stablecoins often fall under new or hybrid regimes that are still maturing.
In terms of infrastructure, tokenized deposits are currently concentrated in permissioned, institution-focused networks; stablecoins are prevalent on public chains and in open DeFi ecosystems.
From a user perspective, tokenized deposits feel like "bank money with new rails," while stablecoins feel like "crypto-native cash equivalents" with different risk and access characteristics.
As digital finance matures, these categories may converge or spawn new hybrids, but for now, understanding their differences is essential for anyone designing, using, or regulating on-chain money. The choice between them is not simply technical; it is a decision about legal protections, regulatory oversight, and the trade-offs between openness and control that will define the next phase of financial infrastructure.
