Explainable AI in Financial Services: What Teams Need to Know
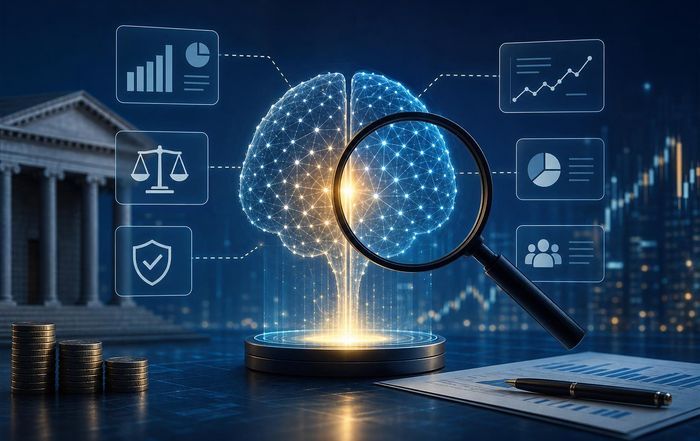
Artificial intelligence is now embedded across modern financial services, from credit scoring and fraud detection to algorithmic trading and wealth management. Yet as models grow more complex, regulators, customers, and internal risk teams are demanding something that many AI systems do not naturally provide: understandable reasoning. This is where explainable AI (XAI) becomes central to how banks, insurers, and fintechs design and deploy models.
Explainability is no longer a niche technical concern. It cuts across regulation, model risk management, customer trust, and even competitive strategy. For teams building or buying AI systems, the key questions are shifting from "Does it work?" to "Can we explain how and why it works, to whom, and at what cost?"
This page examines what explainable AI really means in a financial context, why it matters, how regulations are evolving, and what practical steps teams can take to embed explainability into their AI lifecycle.
What explainable AI actually means in finance
Explainable AI refers to methods and practices that make the behavior and outputs of AI systems understandable to humans. In financial services, this is not a purely academic goal; it is tied directly to legal obligations, supervisory expectations, and business risk.
Two complementary ideas are crucial:
Transparency of the model itself (global explainability).This is about understanding the overall logic of a model: which features matter most, how they interact, whether the model behaves reasonably across different segments, and where it may be fragile or biased. For example, a credit risk team might want to know whether a model is overly sensitive to short credit histories or specific geographies.
Explanation of individual decisions (local explainability).This is about being able to explain why a specific loan was declined, why a particular transaction was flagged as suspicious, or why a robo-advisor recommended a given portfolio. Local explanations are often needed to comply with consumer protection rules and to respond to customer complaints.
In practice, explainability spans multiple layers:
Model architecture and features (e.g., using more interpretable model classes where appropriate, or limiting feature complexity in high-stakes use cases).
Post-hoc explanation tools such as feature importance, partial dependence, counterfactual explanations, and methods like SHAP or LIME.
Documentation and governance that describe data sources, assumptions, training processes, and validation results in language stakeholders can understand.
Human-centered presentation of explanations so they are meaningful for different audiences: model validators, frontline staff, regulators, and end customers.
Explainability is therefore not just a tool or metric; it is a design principle that should influence model choice, data treatment, and how decisions are communicated.
Why explainability is becoming a strategic issue
Financial firms are under simultaneous pressure from regulators, customers, and internal risk functions to make AI more transparent.
From a regulatory perspective, supervisors such as the European Banking Authority (EBA), the Bank of England and Prudential Regulation Authority (PRA) in the UK, and agencies like the U.S. Federal Reserve and Consumer Financial Protection Bureau (CFPB) have all emphasized model risk management, fairness, and accountability in automated decision-making. While each jurisdiction uses different terminology, many expectations converge on similar themes: firms must understand and be able to justify the behavior of models that affect customers and financial stability.
Regulators are increasingly focusing on:
Fair treatment and non-discrimination.Credit, insurance pricing, and employment-related models must not produce unlawful bias. Explainability supports bias testing and remediation, and helps demonstrate compliance with anti-discrimination laws enforced by bodies such as the U.S. Equal Employment Opportunity Commission (EEOC) or national equality regulators in Europe.
Consumer rights to information.Under data protection regimes such as the EU's GDPR, consumers may have rights to meaningful information about the logic involved in automated decisions. While interpretations vary, firms need a defensible approach to explaining high-impact decisions.
Model risk and governance.Supervisory guidance on model risk management, such as the Federal Reserve's SR 11-7 framework in the U.S., expects firms to validate and monitor models rigorously. For complex AI, explainability is often essential for effective validation.
Beyond regulation, explainability is becoming a differentiator in customer trust. Consumers are increasingly aware that algorithms affect their access to credit, insurance, and investment opportunities. Being able to provide clear, non-technical reasons for decisions can reduce complaints, improve satisfaction, and support responsible innovation.
Finally, explainability is crucial for internal alignment. Senior management, boards, and risk committees need to understand how AI systems drive key metrics. Without credible explanations, it is harder to obtain approvals, allocate capital, or respond to crises when models fail.
Regulatory and policy trends teams must track
The regulatory landscape around AI and explainability is evolving quickly, and financial institutions need to follow both sector-specific and cross-sector AI rules.
In the European Union, the EU AI Act is setting a comprehensive framework for AI systems, including many used in finance. Creditworthiness assessments, insurance risk scoring, and certain HR systems are expected to fall under "high-risk" categories, which trigger requirements around risk management, data governance, documentation, human oversight, and transparency. While the Act is horizontal (not finance-specific), it will sit alongside sectoral rules from the European Central Bank (ECB) and EBA, which already emphasize model risk and explainability in banking supervision.
In the United States, there is no single AI law, but multiple agencies are shaping expectations. The CFPB has signaled that lenders must provide specific and accurate reasons for adverse decisions, even when they use complex machine learning, and cannot hide behind "black box" models. The Federal Reserve, Office of the Comptroller of the Currency (OCC), and Federal Deposit Insurance Corporation (FDIC) have issued joint statements on model risk and the use of AI, stressing that existing rules on safety, soundness, and consumer protection apply regardless of technology used. The Securities and Exchange Commission (SEC) is also paying closer attention to AI use in brokerage and investment advisory services, especially where conflicts of interest or misleading communications may arise.
Other jurisdictions are moving in similar directions. The Monetary Authority of Singapore (MAS) has published principles for Fairness, Ethics, Accountability and Transparency (FEAT) in AI and data analytics, encouraging financial institutions to make AI-driven decisions explainable and accountable. The Financial Conduct Authority (FCA) in the UK has explored AI explainability in consumer finance and is integrating AI considerations into its broader conduct and operational resilience agenda.
For teams, the key takeaway is that explainability is not optional for high-impact models. It is becoming embedded in regulatory expectations, and firms should assume that supervisors will ask not only whether a model is accurate, but also how it can be understood, monitored, and challenged.
Where explainable AI matters most in the financial stack
AI is being deployed across a wide range of financial use cases, but some applications are especially sensitive and therefore demand stronger explainability.
In credit underwriting and lending, models determine who receives loans, at what price, and under what terms. These decisions directly affect financial inclusion and can raise discrimination risks. Lenders increasingly use machine learning to augment traditional credit scores, drawing on alternative data such as transaction histories or behavioral indicators. To meet regulatory and ethical expectations, these models must support clear reasons for approvals and denials, robust fairness testing, and transparent documentation of data sources and feature engineering. Internal teams often pair advanced models with more interpretable scorecards or overlays to balance performance and explainability.
In fraud detection and anti-money-laundering (AML), explainability plays a different but equally important role. Transaction monitoring systems generate alerts that analysts must review quickly. Highly opaque models can overwhelm teams with false positives or obscure why a transaction is suspicious. Explainable AI can highlight the key risk factors driving an alert-such as unusual counterparties, transaction patterns, or geographic anomalies-helping investigators prioritize cases and create better narratives for suspicious activity reports. Supervisors and law enforcement agencies, including bodies like the Financial Action Task Force (FATF) and national financial intelligence units, increasingly expect firms to understand and be able to justify their detection logic.
In trading, portfolio management, and robo-advisory, AI models influence investment decisions and risk management. Explainability helps investment committees and risk officers understand the drivers of portfolio risk, factor exposures, and scenario behavior. For retail robo-advisors, clear explanations of portfolio recommendations, risk profiles, and rebalancing actions are essential to comply with suitability and disclosure rules set by regulators such as the SEC or the FCA, and to maintain client confidence.
Other areas where explainability is gaining traction include insurance pricing and underwriting, collections and debt management, and customer marketing and personalization. In each case, the appropriate depth and form of explanation will differ, but the core need to understand and justify automated decisions is consistent.
For readers looking to connect explainable AI with broader fintech trends, related topics such as AI in financial operations and digital banking are explored in more depth on our AI, fintech, and banking sections.
Technical approaches: from simple models to post-hoc explanations
From a technical standpoint, there is no single "best" approach to explainable AI. Instead, teams must balance accuracy, complexity, performance, and interpretability according to the risk and regulatory profile of each use case.
One strategy is model choice for interpretability. In some high-stakes settings, firms may prefer inherently interpretable models such as generalized linear models, decision trees, or scorecards, even if more complex models could theoretically yield marginal performance gains. For example, many credit risk models still rely on logistic regression or constrained gradient boosting because they are easier for validators and regulators to understand, and because their behavior is more stable under changing conditions.
Another strategy involves post-hoc explanation methods applied to complex models such as gradient boosting machines, random forests, or deep learning. Techniques like SHAP (SHapley Additive exPlanations) and LIME (Local Interpretable Model-agnostic Explanations) estimate feature contributions to individual predictions, helping teams understand why a model produced a specific output. Global feature importance and partial dependence plots can reveal how features generally influence predictions, while counterfactual explanations can show how small changes in inputs might alter an outcome (for instance, how much a borrower would need to reduce their debt-to-income ratio to qualify for a loan).
However, post-hoc explanations have limitations. They provide approximations rather than direct access to a model's internal reasoning, and different methods can sometimes yield conflicting results. Over-reliance on post-hoc tools without understanding their assumptions can create a false sense of transparency. Supervisors and model risk teams are increasingly aware of these issues and may expect firms to justify not only their models but also their chosen explanation techniques.
For teams working with generative AI-such as large language models used in customer service, document analysis, or coding assistance-explainability challenges can be even greater. These models are often trained on vast, heterogeneous datasets, and their internal representations are difficult to interpret. In such cases, explanation strategies may focus more on system-level controls: constrained prompts and templates, retrieval-augmented generation with clear source citations, human-in-the-loop review, and robust output monitoring. Organizations like OpenAI, Google, and Microsoft are investing heavily in research on interpretability and responsible AI, but financial firms should not assume that vendor-provided tools automatically satisfy regulatory expectations.
Explainability, bias, and fairness: deeply connected concerns
Explainability and fairness are closely linked in financial services. Many of the most sensitive AI use cases-credit, insurance, hiring, and pricing-are also those where historical data may embed social and economic biases.
To assess and mitigate bias, teams must understand how models use input features and how outcomes differ across demographic groups. Explainable AI supports this by:
Revealing which features carry the most weight in decisions, enabling scrutiny of variables that may act as proxies for protected characteristics.
Supporting fairness metrics and stress tests across segments, such as approval rates, error rates, or pricing differentials by gender, race, age, or geography where permitted and legally appropriate.
Enabling targeted model adjustments, such as feature constraints, reweighting, or post-processing of outputs, to reduce disparate impacts while preserving predictive power.
Organizations such as the OECD, World Bank, and various academic centers are producing guidance on responsible AI and fairness in financial inclusion. However, there is often no single "correct" fairness metric, and trade-offs between accuracy, risk, and fairness must be made transparently and documented clearly.
Explainability is therefore both a diagnostic and a communication tool. It helps technical teams understand where bias may arise and provides a basis for explaining fairness choices to regulators, civil society groups, and customers.
Readers interested in the interaction between AI, fairness, and broader economic outcomes can find complementary coverage in our economy, business, and world sections.
Building explainability into model governance and risk management
Explainable AI is not just a feature of individual models; it is a pillar of modern model risk management. Effective governance requires explainability to be embedded across the model lifecycle.
During model design and development, teams should classify use cases by risk and regulatory impact, and choose modeling approaches accordingly. For high-impact decisions, it may be appropriate to prioritize interpretable models or to set explicit constraints on features and complexity. Data lineage, transformations, and feature engineering choices should be documented in a way that non-technical stakeholders can follow.
In validation and testing, explainability supports robust challenge. Independent model risk teams can use feature importance analysis, sensitivity testing, and scenario analysis to probe model behavior. Where post-hoc tools are used, validators should understand their limitations and test whether explanations are stable and consistent. Stress tests should examine how models behave when key assumptions break down or when input distributions shift.
For deployment and monitoring, explainability helps identify model drift, performance degradation, and emerging fairness issues. Dashboards that track feature distributions, outcome metrics, and explanation patterns across segments can alert teams when behavior deviates from expectations. In some cases, explainability metrics themselves-such as stability of feature importance rankings-can be used as early warning indicators.
Governance frameworks from organizations such as the Basel Committee on Banking Supervision, the Institute of International Finance (IIF), and national supervisors increasingly highlight the importance of explainability in AI governance. Firms that treat explainability as a one-time compliance exercise, rather than an ongoing capability, are likely to struggle as models, data, and regulations evolve.
For teams building careers in this space, our jobs and education sections frequently cover skills and training relevant to AI governance, data science, and risk management roles.
Communicating explanations to different audiences
One of the most underestimated aspects of explainable AI is communication. The same model may need to be explained very differently to customers, frontline staff, risk committees, auditors, and regulators.
For end customers, explanations must be concise, understandable, and actionable. In lending, this often means providing clear reasons for adverse decisions-such as high debt-to-income ratio or limited credit history-along with guidance on what could improve future outcomes. Legal requirements, such as adverse action notices enforced by agencies like the CFPB or equivalent bodies in other jurisdictions, set minimum standards, but firms can go further to build trust and reduce confusion.
For customer-facing staff, explanations should support effective conversations. Relationship managers, call center agents, and branch staff need enough detail to discuss decisions confidently without misrepresenting the model. Training and well-designed tools can help staff interpret model outputs and explanations correctly.
For internal risk, audit, and compliance teams, explanations must be rigorous and traceable. This includes detailed documentation of model design, data sources, validation results, and monitoring plans. Explainability tools should be integrated into model documentation so that reviewers can reproduce and interrogate key findings.
For regulators and supervisors, explanations must align with regulatory frameworks and guidance. Firms should be prepared to demonstrate how explainability supports fairness, consumer protection, and prudential safety, and how it is integrated into governance and control processes. In some cases, supervisors may request access to underlying models, code, or data to conduct their own assessments.
Designing explanation strategies for these different audiences often requires collaboration between data scientists, legal teams, compliance officers, UX designers, and business owners. Firms that invest in this cross-functional communication can turn explainability from a compliance burden into a strategic asset.
Practical steps for teams implementing explainable AI
For teams at banks, insurers, and fintech companies, turning the concept of explainable AI into practice can be challenging. A pragmatic approach often includes the following elements:
First, establish clear policies and risk-based standards. Not all models need the same level of explainability. Firms can classify models by impact-such as customer-facing credit, pricing, and eligibility decisions versus internal forecasting or operational optimization-and set corresponding explainability requirements. High-impact models may require inherently interpretable approaches or multiple explanation methods, while lower-risk models might rely on lighter-weight techniques.
Second, build or adopt a standardized toolkit for explainability. This might include open-source libraries, vendor tools, or in-house platforms that support feature importance analysis, local and global explanations, and fairness testing. Tooling should be integrated into the model development pipeline so that explanations are produced and reviewed as part of standard workflows rather than as an afterthought.
Third, invest in skills and training across teams. Data scientists need to understand regulatory expectations and the limitations of different explanation methods. Risk and compliance professionals need enough technical literacy to challenge models effectively. Business leaders need to understand what explainability can and cannot provide so that they can set realistic expectations and make informed trade-offs.
Fourth, embed explainability into documentation and governance. Model inventories, validation reports, and monitoring dashboards should include explainability artifacts and narrative explanations. Governance bodies such as model risk committees should explicitly consider explainability when approving models, and internal audit should periodically review adherence to explainability standards.
Finally, engage proactively with regulators and industry bodies. As AI regulation continues to evolve, early dialogue can help firms understand supervisory expectations and share practical challenges. Industry groups, academic institutions, and standards organizations are actively exploring explainable AI in finance, and participation in these communities can help teams stay ahead of emerging best practices.
Folks interested in how explainable AI intersects with crypto, green finance, and broader innovation themes will find additional news in our crypto, green-fintech, and security pages.
From compliance requirement to competitive capability
Explainable AI in financial services sits at the intersection of technology, regulation, and trust. While much of the current focus is on meeting supervisory expectations and managing model risk, firms that approach explainability strategically can unlock broader benefits.
Transparent models are easier to debug, adapt, and scale across markets. Clear explanations can reduce customer friction, support financial inclusion, and improve the quality of internal decision-making. Robust explainability practices make it easier to integrate new data sources and AI techniques without losing control or visibility.
As AI systems become more pervasive across finance, the ability to explain them-to regulators, customers, staff, and society at large-will increasingly distinguish institutions that can innovate safely from those that struggle to keep pace. For teams building the next generation of financial services, explainability is not just something to add at the end of a project; it is a design choice that should shape how AI is conceived, developed, and governed from the outset.
