Digital Identity Verification in Modern Banking Onboarding
Digital identity verification has moved from a back-office compliance task to a frontline strategic capability for banks. As more customers open accounts and apply for products entirely online, onboarding has become a decisive moment: get identity checks wrong and institutions risk fraud, regulatory penalties, and customer churn; get them right and they can unlock growth, lower costs, and safer digital ecosystems.
Join as we ponder on how digital identity verification works in modern banking onboarding, the regulatory and technological forces reshaping it, and what financial institutions should prioritize as they redesign customer journeys.
Why digital identity is now central to onboarding
In most major markets, the majority of new banking relationships now start online or on mobile. Challenger banks and neobanks have normalized the idea of opening an account in minutes, forcing incumbent institutions to compress processes that used to take days and multiple branch visits into a single digital flow. At the same time, regulators have tightened expectations on anti-money laundering (AML), counter-terrorist financing (CTF), and sanctions screening, with higher penalties for failures and more scrutiny of remote onboarding.
This convergence means identity verification must now simultaneously achieve three things: satisfy stringent know-your-customer (KYC) and AML rules, stop increasingly sophisticated fraud, and deliver a smooth customer experience that matches digital-first competitors. Readers interested in the broader fintech implications can find more context in our coverage of fintech innovation and digital banking.
Banks also operate in a landscape where national digital ID schemes, open banking frameworks, and real-time payment systems are raising expectations for instant, secure verification. Regulators such as the Financial Action Task Force (FATF) now explicitly recognize digital identity systems and provide guidance on their use in customer due diligence, while supervisors in the EU, UK, US, and Asia increasingly expect institutions to understand, test, and govern the technologies they deploy.
Regulatory foundations: KYC, AML, and risk-based onboarding
Any discussion of digital identity verification in banking has to start with regulation. While specific rules differ by jurisdiction, there is broad convergence around several key elements.
Most banks must comply with AML and CTF regimes, typically aligned with FATF recommendations, which require effective customer due diligence, ongoing monitoring, and reporting of suspicious activity. In the EU, the evolving AML package and the planned EU Digital Identity Wallet initiative are reshaping how remote onboarding can be performed. The European Banking Authority (EBA) has issued guidelines on remote customer onboarding, emphasizing secure processes, independence of checks, and governance over third-party providers. In the UK, the Financial Conduct Authority (FCA) expects firms to apply a risk-based approach and has published guidance on financial crime systems and controls that encompass digital onboarding.
In the US, banks must follow the Customer Identification Program (CIP) rules under the Bank Secrecy Act, overseen by bodies such as FinCEN (fincen.gov) and banking regulators coordinated through the FFIEC (ffiec.gov). These rules specify minimum information to collect and require reasonable belief that the institution knows the true identity of its customers. Remote onboarding is permitted but must be supported by robust, well-documented controls.
Across Asia, regulators such as the Monetary Authority of Singapore (MAS) and the Hong Kong Monetary Authority (HKMA) have been comparatively proactive in enabling non-face-to-face onboarding, often issuing detailed guidance on the use of biometric verification, video KYC, and trusted national databases.
Despite these differences, a few regulatory themes are consistent: institutions must understand the limitations of digital tools, perform appropriate testing and oversight, and calibrate the intensity of verification to customer risk. Higher-risk relationships, such as cross-border private banking or complex corporate structures, typically require enhanced due diligence that goes beyond standard digital checks.
Core components of digital identity verification
Modern digital onboarding usually brings together several layers of verification. The exact mix depends on jurisdiction, risk appetite, and product type, but a typical stack includes document checks, biometric verification, data and device intelligence, and ongoing monitoring.
Document verification remains a cornerstone. Customers are asked to capture images of government-issued IDs such as passports or national identity cards. Advanced solutions apply optical character recognition (OCR), document template matching, security feature analysis, and machine-learning models to detect tampering, forgeries, or recycled images. Many vendors cross-check document data against authoritative sources such as government registries or credit bureaus where regulations permit.
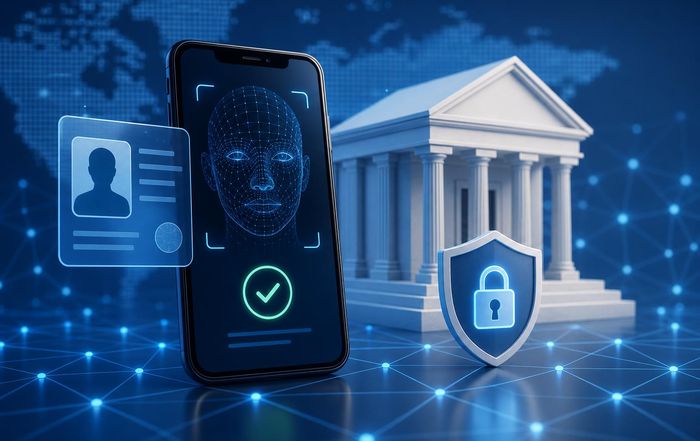
Biometric verification adds a second dimension: confirming that the person presenting the document is the same as the one captured in the ID, and that they are physically present. Face matching compares a selfie or short video with the photo on the identity document, while liveness detection looks for signs of spoofing, such as static images, deepfakes, or replay attacks. Standards bodies like the FIDO Alliance (fidoalliance.org) and the National Institute of Standards and Technology (NIST) have helped define performance and security benchmarks for biometric authentication and identity assurance.
Data-driven verification complements these steps by checking identity attributes against external data sources-such as credit reference agencies, address databases, phone records, sanctions lists, and politically exposed persons (PEP) registers-often through specialist providers. Device and behavioral intelligence add another layer: IP address risk, device fingerprinting, velocity checks, and behavioral analytics help detect synthetic or stolen identities and coordinated fraud attempts.
Finally, modern onboarding is tightly integrated with ongoing AML monitoring systems. Customer risk scores, watchlist matches, and transactional behavior feed back into the risk profile, allowing institutions to apply dynamic controls and, in some cases, step-up verification when anomalies appear. For readers tracking how this interacts with broader economy and regulation trends, this convergence between onboarding and transaction monitoring is becoming a key supervisory focus.
The role of AI and machine learning in verification
Artificial intelligence now underpins much of digital identity verification, particularly in image analysis, anomaly detection, and decision automation. Convolutional neural networks power document and face recognition, while gradient-boosting and deep learning models help detect patterns indicative of synthetic identities or organized fraud that rule-based systems might miss. Vendors increasingly offer pre-trained models tuned to specific document types and local fraud patterns, reducing the operational burden on banks.
However, the use of AI in identity verification is not without challenges. Bias in facial recognition performance across demographic groups has been documented by entities such as NIST, raising concerns about fairness and potential discrimination. Regulators and privacy authorities, including the European Data Protection Board (edpb.europa.eu), have signaled that automated decision-making in high-impact areas like access to financial services must be explainable and subject to human oversight. Banks must therefore balance automation with clear governance, auditability, and recourse mechanisms.
Generative AI has added a new dimension both to fraud and to defense. On the one hand, it can be used to create highly realistic forged documents, synthetic voices, and deepfake videos that challenge traditional liveness checks. On the other, it can support analysts in investigating suspicious patterns, summarizing case files, and simulating attack scenarios. Institutions experimenting with these tools need strong model-risk management, a topic increasingly discussed by regulators such as the European Central Bank (ecb.europa.eu) in the context of digital transformation.
For readers particularly interested in AI's role across financial services, our AI in finance coverage explores how similar technologies are being deployed in credit scoring, trading, and operational risk.
Customer experience: balancing friction and security
From a customer's perspective, onboarding is often their first real interaction with a bank's digital capabilities. If identity checks are confusing, slow, or intrusive, abandonment rates rise and acquisition costs climb. Yet relaxing controls to reduce friction can quickly lead to higher fraud losses and regulatory risk. The art lies in applying friction intelligently.
Well-designed digital flows guide users through ID capture and liveness checks with clear instructions, real-time feedback, and graceful error handling. For many institutions, this means investing in user-experience research and localization: different markets have different expectations about privacy, comfort with biometrics, and the types of documents they commonly hold. Accessibility is another critical factor; onboarding flows should be usable by customers with disabilities and on lower-end devices or slower network connections, particularly in emerging markets where smartphone diversity is high.
Risk-based orchestration platforms are increasingly used to tailor the level of verification to the situation. A low-risk domestic savings account with small transaction limits may justify a lighter process, while a high-limit cross-border payment account might trigger more extensive checks, including video interviews or additional documentation. Behavioral analytics can also reduce friction by allowing trusted returning users to complete subsequent product applications with minimal additional verification, building on a strong initial identity proofing.
Banks that get this balance right often integrate identity verification into broader digital journeys, such as instant card issuance, digital wallets, or investment onboarding. This is closely tied to the competitive dynamics covered in our business and strategy reporting, where customer lifetime value depends heavily on the quality of early digital interactions.
Fraud trends and evolving threat models
As banks have strengthened their defenses, fraudsters have shifted tactics. Instead of relying solely on stolen IDs, they increasingly construct synthetic identities-blending real and fabricated data-to pass automated checks and slowly build credit histories before executing large-value fraud. Synthetic identity fraud has become a significant issue in markets such as the US, where large, diverse data sets and social security numbers can be exploited.
Account takeover also remains a major threat. Even when onboarding checks are strong, weak downstream authentication, phishing, and social engineering can allow criminals to hijack legitimate accounts. This is one reason why regulators and industry groups, including EMVCo (emvco.com) and ISO (iso.org), have pushed for stronger multi-factor authentication and secure payment protocols.
The rise of real-time payments has compressed the window in which banks can detect and stop fraudulent activity. Faster clearing means less time to investigate anomalies before funds leave the system, making robust upfront identity proofing even more critical. At the same time, "authorized push payment" scams-where customers are tricked into sending money themselves-highlight that identity verification alone cannot solve all fraud; consumer education, transaction-level monitoring, and liability frameworks also matter. Our security section regularly explores how banks are adapting to these blended threats.
To respond, many institutions are integrating identity verification with broader fraud platforms, sharing signals across onboarding, login, and transaction stages. Consortium data and industry utilities are also gaining traction, allowing banks to share anonymized intelligence on risky devices, email addresses, or behavioral patterns while attempting to respect data-protection rules.
Privacy, data protection, and ethical considerations
Digital identity verification involves collecting and processing some of the most sensitive categories of personal data, including biometric templates, document images, and sometimes geolocation and behavioral signals. In jurisdictions governed by frameworks such as the EU's GDPR or similar privacy laws in regions like California and Brazil, banks must have a clear legal basis for processing, minimize data collection, and ensure robust security and retention policies.
Biometric data, in particular, is often treated as a special category requiring explicit consent or strong justification. Institutions need to explain why they are using biometrics, how long data will be stored, whether it will be shared with third parties, and how customers can exercise their rights. Privacy regulators have taken enforcement action against companies misusing biometric data or failing to properly secure it, underlining the need for careful governance.
Ethical questions also arise around exclusion and fairness. Customers without standard identity documents, stable addresses, or credit histories can be disadvantaged by digital-only processes. This is especially relevant for migrants, refugees, gig workers, and people in informal economies. International organizations such as the World Bank (worldbank.org) and ID4D have highlighted the importance of inclusive, trusted identity systems for financial inclusion. Banks designing onboarding journeys must therefore consider alternative verification routes, partnerships with national digital ID schemes, and manual review paths that avoid permanently excluding legitimate customers.
These issues intersect with broader sustainability and inclusion themes we explore in our environment and green fintech and education coverage, where digital infrastructure can both enable and hinder equitable access to finance.
National digital ID schemes and reusable identity
A growing number of countries are deploying national digital identity systems that can be used for banking onboarding. Examples include the Nordic BankID ecosystems, India's Aadhaar-linked e-KYC, and the EU's planned interoperable digital identity framework. These schemes promise to reduce onboarding friction, lower costs, and improve assurance by allowing banks to rely on credentials issued or verified by governments or certified identity providers.
From a bank's perspective, reusable digital identity can transform onboarding from a one-off verification into a recurring trust relationship. Customers might authenticate using a government-backed wallet and consent to share verified attributes, such as name, age, and address, without repeatedly uploading documents. This model aligns with emerging concepts of "self-sovereign identity," where users control which data they share and with whom.
However, relying on external identity providers creates dependencies and new risk vectors. Banks must assess the assurance level of the digital ID scheme, understand liability frameworks, and ensure that their own AML obligations are still met. Interoperability is another challenge: cross-border banking relationships often involve customers from jurisdictions with very different identity infrastructures. Standards work by bodies like the OpenID Foundation (openid.net) and the W3C (w3.org) on verifiable credentials and identity protocols aims to address some of these issues, but large-scale, seamless interoperability remains a work in progress.
The intersection between national digital IDs, open banking, and cross-industry identity is likely to be a major theme in the evolution of fintech, and is closely linked to developments we track in world and global finance.
Organizational and operational challenges for banks
Implementing modern digital identity verification is not simply a technology procurement exercise. It affects operating models, governance, staffing, and even product design. Banks must decide whether to build capabilities in-house, partner with specialist vendors, or adopt a hybrid approach. Vendor selection involves assessing not only technical accuracy and coverage, but also regulatory compliance, data-protection posture, financial stability, and alignment with the bank's geographic footprint.
Integration is often complex. Identity verification tools must interact with core banking systems, CRM platforms, AML transaction monitoring, sanctions screening, and sometimes external data sources. Orchestration layers are increasingly used to manage different verification paths, support A/B testing of onboarding flows, and quickly adapt to new regulations or fraud patterns.
From an organizational perspective, close collaboration is needed between compliance, risk, IT, product, and customer-experience teams. Compliance may push for more stringent checks, while product teams advocate for speed and simplicity; successful institutions create governance forums that can make informed trade-offs based on data. Training is also critical: front-line staff, operations teams, and even marketing need to understand the basics of digital identity verification to respond to customer queries and spot anomalies.
These organizational shifts have implications for financial sector employment and skills, themes we examine in our jobs and careers coverage, where demand is rising for professionals with blended expertise in compliance, data science, and UX.
How digital identity is reshaping competition in banking
Digital identity verification has become a competitive differentiator. Neobanks and fintechs often market "account opening in minutes" as a core value proposition, built on streamlined document capture and automated decisioning. Incumbent banks that still rely on manual back-office checks or branch visits risk losing digitally savvy customers and small businesses to more agile competitors.
At the same time, incumbents hold advantages: large customer bases, historical data, and often closer relationships with regulators. Many are now leveraging these to build sophisticated digital onboarding platforms that can be reused across business lines and even offered "as a service" to partners in embedded finance arrangements. This blurs the line between traditional banks and fintech infrastructure providers.
Cryptoasset platforms and digital-only investment firms have also had to upgrade their onboarding as regulators extend AML rules to virtual asset service providers. This has increased convergence between the identity practices of traditional finance and crypto, an area we analyze in our crypto and stock-exchange and markets reporting. Institutions that can offer compliant, low-friction onboarding across both traditional and digital assets may gain an edge with younger, globally mobile customers.
Ultimately, the institutions that will thrive are those that treat digital identity not just as a compliance obligation, but as a strategic asset-one that underpins trust, enables personalization, and supports innovation in products and channels.
Where digital identity in onboarding is heading
Looking ahead, several trends are likely to shape the next phase of digital identity verification in banking. First, convergence between authentication and identity proofing will continue. Customers may use the same strong credentials-such as passkeys or certified mobile IDs-for both logging in and proving who they are to new providers, reducing fragmentation and password fatigue.
Second, privacy-preserving technologies such as zero-knowledge proofs and selective disclosure of attributes could allow banks to verify specific facts (for example, that a customer is over 18 or resides in a given country) without accessing full underlying documents. This would address some data-minimization concerns and could become more common as standards mature.
Third, regulators are likely to become more prescriptive about the governance of AI and biometrics in identity verification, moving from high-level principles to detailed expectations on testing, monitoring, and incident reporting. Banks that invest early in explainability, bias mitigation, and robust model-risk management will be better positioned as these rules crystallize.
Finally, collaboration across sectors-banks, telecoms, governments, and technology providers-will be critical. No single institution can solve digital identity in isolation, particularly in cross-border contexts. Industry utilities, shared digital ID schemes, and interoperable wallets will play an increasing role in how customers are onboarded, authenticated, and served across the financial ecosystem.
For financial institutions, the strategic question is no longer whether to digitize onboarding, but how to architect identity verification so that it is secure, inclusive, adaptable, and a source of long-term competitive advantage.
