How Embedded Lending Is Changing Business Finance
A New Operating System for Business Finance
Embedded lending has shifted from a promising innovation to a structural change in how businesses access and manage capital. Rather than approaching banks or traditional lenders as a separate step, enterprises now increasingly obtain credit at the point of need, inside the software and platforms they already use to run their operations. This quiet but profound transformation is reshaping working capital management, customer financing, supply chain relationships and even how founders design new business models, and it is at the center of the daily editorial and analytical focus here.
The concept of embedded lending is simple but powerful: credit products are integrated directly into non-financial customer journeys, whether in B2B marketplaces, enterprise resource planning systems, e-commerce platforms, payroll tools or point-of-sale applications. A business can request, receive and repay financing without leaving its primary digital environment. By combining real-time data, advanced analytics and modern cloud infrastructure, embedded lenders are able to underwrite risk more dynamically and tailor offers to the specific context of a transaction, which is radically different from the static, document-heavy processes that have defined traditional commercial lending for decades.
For readers tracking the evolution of fintech and digital business models on FinanceTechX's fintech coverage, embedded lending illustrates how finance is becoming less a standalone industry and more a horizontal capability woven into every digital workflow, much as cloud computing and APIs did for software.
From Product to Infrastructure: Why Embedded Lending Matters Now
The acceleration of embedded lending since 2020 is the result of several converging forces in technology, regulation and business behavior. Cloud-native banking infrastructure, open banking frameworks and the rise of application programming interfaces have allowed both banks and non-bank providers to expose credit capabilities as modular services rather than closed products. At the same time, the widespread adoption of digital platforms in sectors such as retail, logistics, manufacturing and professional services has created natural distribution channels for financing that sit much closer to the point of economic activity.
Organizations such as McKinsey & Company have documented how banking is moving toward a "platform and ecosystem" model in which financial services are increasingly embedded into broader customer journeys rather than delivered in isolation. Learn more about the evolution of platform-based banking through resources from McKinsey on Banking. This shift is particularly evident in small and medium-sized enterprise finance, where the administrative burden of traditional credit applications has long been a barrier to growth and innovation.
Embedded lending also aligns with regulatory and market trends that favor competition and innovation in financial services. Open banking regulations in the European Union, the United Kingdom and other jurisdictions have encouraged data portability and interoperability, enabling third-party providers to access bank data securely, with customer consent, and use it for alternative underwriting models. The European Banking Authority and the UK Financial Conduct Authority have both published extensive guidance on digital finance, data usage and consumer protection, which can be explored in more depth through the European Banking Authority's digital finance pages and FCA's innovation and fintech resources.
For a business audience focused on strategy, growth and resilience, as reflected in FinanceTechX's business section, embedded lending matters because it changes the economics of access to capital. It can reduce friction, lower transaction costs, and in many cases provide more tailored, data-driven credit that better reflects the real-time health of a firm rather than backward-looking financial statements alone.
How Embedded Lending Works in Practice
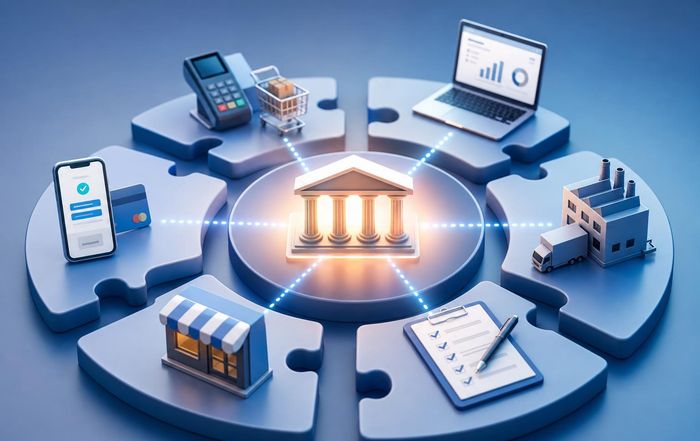
Although the term "embedded lending" covers a broad range of models, the underlying architecture typically involves four key actors: the digital platform that owns the customer relationship, the lender or balance sheet provider, the technology enabler that provides APIs and orchestration, and the end business that receives financing. The platform, which may be an e-commerce marketplace, B2B procurement site, accounting system or vertical SaaS tool, integrates lending functionality through APIs, allowing its users to apply for and manage loans without leaving the platform.
The lender, which might be a regulated bank, a licensed non-bank financial institution or a specialist credit fund, provides the capital and underwriting policies. Technology enablers such as Stripe, Shopify, Klarna, Adyen or newer infrastructure players in the B2B space often provide the middleware that connects platforms to lenders, manages data flows, orchestrates identity and risk checks, and ensures compliance with local regulations. To understand how global payment and credit infrastructure is evolving, readers can explore insights from the Bank for International Settlements on digital payments and new financial market infrastructures.
In many cases, the underwriting engine leverages rich data from the platform itself: sales volumes, order histories, invoice payment patterns, shipping data, subscription churn and even customer review metrics can inform risk models. This is where embedded lending intersects with the rise of artificial intelligence and advanced analytics, a topic that FinanceTechX covers extensively in its dedicated AI and financial technology section. Machine learning models can identify patterns that traditional scorecards might miss, enabling more nuanced decisions, particularly for thin-file or younger businesses that lack extensive credit histories.
Repayment is often structured to align with cash flows. For example, a merchant cash advance embedded within an e-commerce platform might be repaid automatically as a fixed percentage of daily sales, reducing the risk of missed payments and smoothing the borrower's cash management. In B2B embedded lending, invoice financing or dynamic discounting solutions may be triggered automatically when an invoice is issued, with repayment occurring when the buyer settles the bill. The operational experience is designed to be almost invisible, with financing becoming part of the natural rhythm of business transactions rather than a separate, time-consuming event.
Sector-Specific Transformations Across Regions
Embedded lending is not a monolithic phenomenon; its impact varies across sectors and geographies, reflecting local regulatory regimes, digital adoption rates and industry structures. In North America and Europe, where digital commerce and SaaS penetration are high, embedded lending has gained particular traction in retail, hospitality, professional services and the broader small business economy. Platforms such as Amazon, PayPal, Square (now Block) and Shopify have built sizable lending portfolios by leveraging the data and relationships within their ecosystems. Analysts can follow developments in these markets through resources from the U.S. Small Business Administration and the European Commission's digital finance initiatives.
In Asia, embedded lending has been strongly influenced by the super-app model, with companies such as Ant Group, Tencent, Grab and GoTo integrating credit into payments, ride-hailing, food delivery and merchant services. These platforms have demonstrated how alternative data, including behavioral and transactional signals from non-financial activities, can inform credit decisions for both consumers and micro-businesses. For broader context on digital finance trends in Asia, readers may consult the Monetary Authority of Singapore and its resources on digital banking and fintech.
In emerging markets across Africa and South America, embedded lending is closely linked to financial inclusion and the digitization of informal or semi-formal economic activity. Mobile money platforms, agritech marketplaces and logistics networks are embedding credit to support smallholder farmers, informal retailers and transport operators. Organizations such as the World Bank and the International Finance Corporation have highlighted how digital financial services can support inclusive growth; interested readers can explore their research on digital financial inclusion.
For the FinanceTechX audience, which spans the United States, Europe, Asia-Pacific, Africa and Latin America, the common thread is that embedded lending is redefining competitive dynamics in multiple industries. It is no longer only banks that decide who receives credit; platforms controlling data and customer access increasingly shape the flow of capital, raising important strategic questions for incumbents and challengers alike.
Impact on Business Models and the Real Economy
Embedded lending is not just a new distribution channel for credit; it is reshaping business models across sectors and influencing macroeconomic patterns. For small and medium-sized enterprises, which form the backbone of most economies, easier access to working capital at the point of need can support investment, hiring and innovation. When financing is integrated into procurement platforms, for example, businesses can secure short-term credit to purchase inventory or raw materials more efficiently, smoothing production cycles and improving supplier relationships.
From a macroeconomic perspective, institutions such as the International Monetary Fund have noted that improved credit access for SMEs can contribute to higher productivity and more resilient growth, provided that risk is managed appropriately. Readers can explore how SME finance and digital lending intersect with broader economic trends through IMF analysis on financial sector developments. Embedded lending may also influence labor markets, as businesses with more predictable access to capital are better positioned to create and sustain jobs, an area of particular interest to those following FinanceTechX's coverage of jobs and skills in the financial technology economy.
At the same time, embedded lending is prompting established financial institutions to rethink their role. Some banks are choosing to become infrastructure providers, offering their balance sheets and regulatory licenses to fintech platforms and non-financial companies through banking-as-a-service arrangements. Others are building their own embedded solutions, partnering with large platforms or developing white-label offerings for vertical software providers. This strategic shift reflects a broader transition in banking from product manufacturing to service enablement, a theme explored in depth by organizations such as the Bank of England in their work on the future of finance and digital transformation.
For founders and executives, as profiled in FinanceTechX's founders section, embedded lending opens the door to new revenue streams and customer engagement models. Platforms that embed credit can capture a share of lending economics, deepen loyalty and differentiate themselves in crowded markets, but they also assume new responsibilities around compliance, data governance and risk management.
Data, AI and Risk: The New Foundations of Trust
Embedded lending relies heavily on data and artificial intelligence, both for underwriting and for ongoing monitoring of credit risk. Transactional data from payment processors, sales platforms, inventory systems and logistics networks can provide a more granular and timely view of a business's health than traditional financial statements alone. When combined with external data sources and macro indicators, this information allows lenders to adjust credit lines dynamically, flag early signs of stress and, in some cases, offer proactive restructuring or support.
However, the reliance on advanced analytics raises critical questions around algorithmic fairness, explainability and governance. Regulators and standard-setting bodies, including the OECD and the Financial Stability Board, have emphasized the need for robust frameworks to ensure that AI-driven credit decisions do not inadvertently reinforce biases or create opaque risk concentrations. To understand emerging global principles on trustworthy AI and financial stability, readers can review resources from the OECD's AI policy observatory and the Financial Stability Board's fintech and innovation work.
For embedded lenders and their partners, building trust requires more than technical sophistication; it demands transparent communication, clear disclosures and robust data protection. As cyber threats grow in scale and sophistication, the security of embedded finance infrastructures becomes a board-level concern. This is an area where FinanceTechX places particular emphasis in its security and cyber-risk coverage, given that breaches or data misuse in embedded lending ecosystems can have systemic implications across multiple platforms and regions.
The interplay between AI, data and regulation is dynamic. In the United States, Europe and parts of Asia, policymakers are actively refining rules on data usage, consumer protection and AI governance. Businesses that rely on embedded lending must therefore invest in compliance capabilities and maintain close dialogue with regulators, industry bodies and civil society organizations to ensure that innovation does not outpace safeguards.
Regulatory and Compliance Considerations Across Jurisdictions
Because embedded lending blurs the boundaries between financial and non-financial services, it raises complex regulatory questions. Who is ultimately responsible for compliance when a loan is originated through a non-bank platform but funded by a regulated institution? How should cross-border data flows and differing local rules on consumer and SME protection be managed when platforms operate globally? These questions are at the forefront of policy debates in key markets.
In the European Union, initiatives such as the Digital Operational Resilience Act (DORA) and the broader digital finance strategy aim to ensure that financial services delivered through digital channels, including embedded models, remain secure and resilient. Businesses can learn more about these frameworks and their implications through the European Commission's digital finance pages. In the United States, agencies such as the Consumer Financial Protection Bureau and the Office of the Comptroller of the Currency are examining how bank-fintech partnerships and banking-as-a-service arrangements should be supervised to prevent regulatory arbitrage and protect end users; guidance and updates are available via the CFPB's website.
In Asia-Pacific, regulators in jurisdictions such as Singapore, Australia and Japan have adopted sandbox and innovation hub models to engage with embedded finance providers while maintaining oversight. The Australian Prudential Regulation Authority and the Australian Securities and Investments Commission, for example, have published guidance on fintech and responsible lending, which can be explored through their respective sites, including ASIC's fintech resources.
For multinational businesses and platforms, the result is a patchwork of requirements that must be navigated carefully. Compliance is no longer just a matter for banks; any platform embedding lending must understand its obligations regarding customer due diligence, anti-money laundering, data privacy and dispute resolution. This complexity reinforces the importance of partnering with experienced financial institutions and technology providers that can help orchestrate multi-jurisdictional compliance.
Embedded Lending, Capital Markets and the Stock Exchange Nexus
As embedded lending portfolios grow, their relationship with capital markets and the broader financial system becomes more significant. Many embedded lenders, particularly non-bank providers, rely on securitization, warehouse lines or partnerships with institutional investors to fund their loan books. This creates new linkages between platform-based credit and bond markets, asset-backed securities and even structured products.
For investors and analysts tracking developments in equity and debt markets, as covered in FinanceTechX's stock exchange analysis, embedded lending introduces both opportunities and new dimensions of risk. On the one hand, data-rich, short-duration SME lending portfolios can offer attractive, diversifying returns, especially when underpinned by robust analytics and real-time performance monitoring. On the other hand, the rapid scaling of such portfolios, particularly in less regulated segments, may create pockets of vulnerability if underwriting standards weaken or macroeconomic conditions deteriorate.
Rating agencies, central banks and international organizations are beginning to pay closer attention to these dynamics. The Bank for International Settlements and national central banks have highlighted the need to monitor non-bank credit intermediation and its interaction with traditional banking. Investors considering exposure to embedded lending assets must therefore assess not only financial metrics but also the quality of data, technology governance and platform risk management.
Talent, Skills and the Future of Work in Embedded Finance
The rise of embedded lending is reshaping talent needs across finance, technology and risk management. Banks, fintech firms and non-financial platforms all require professionals who can bridge disciplines: data scientists who understand credit, risk officers who grasp API architectures, compliance experts who can interpret evolving digital finance regulations, and product managers who can design seamless, ethical embedded experiences.
For professionals and students following FinanceTechX's education and career insights, embedded lending represents a fertile area for upskilling and specialization. Universities, professional bodies and online learning platforms are expanding programs in digital finance, AI in credit risk, regulatory technology and platform strategy. Organizations such as the Chartered Financial Analyst Institute and the Global Association of Risk Professionals offer resources and certifications that increasingly incorporate fintech and data-driven risk management, which can be explored via the CFA Institute's future of finance initiatives.
At the same time, embedded lending has implications for the broader workforce, particularly in small businesses and entrepreneurial ecosystems. Easier access to credit can support job creation and business formation, but it may also accelerate competitive pressures as more firms can scale quickly. Leaders must therefore consider how to invest in human capital, digital skills and organizational resilience to make the most of new financing tools while managing volatility.
Sustainability, Green Fintech and Responsible Embedded Credit
As environmental, social and governance (ESG) considerations move to the center of corporate strategy, embedded lending is beginning to intersect with sustainability objectives. Green embedded finance models are emerging in sectors such as energy, mobility and construction, where financing is integrated into platforms that support solar installations, electric vehicle fleets or energy-efficient building upgrades. These models can help overcome upfront cost barriers and accelerate the adoption of low-carbon technologies.
For example, energy management platforms and marketplace operators are partnering with banks and specialist lenders to offer embedded loans or leases for clean technology investments, with underwriting informed by projected energy savings and carbon reduction metrics. This aligns with broader trends in sustainable finance, as discussed by organizations such as the UN Environment Programme Finance Initiative, whose work on sustainable banking and green finance provides a useful framework for integrating ESG considerations into lending.
FinanceTechX has been tracking the convergence of green fintech and embedded finance in its dedicated green fintech and environment coverage and environment section, recognizing that access to tailored, embedded credit solutions can be a powerful lever for climate-aligned investment across both developed and emerging markets. As regulatory initiatives such as the EU Taxonomy and disclosure requirements under frameworks like the Task Force on Climate-related Financial Disclosures evolve, embedded lenders and their platform partners will need to align product design, data collection and reporting with these standards.
Top Considerations for Leaders
Embedded lending is no longer an optional experiment; it is a strategic consideration for boards and executive teams across industries. For banks and traditional lenders, the key questions revolve around partnership strategies, technology investment, risk appetite and brand positioning. Should they prioritize white-label infrastructure roles, build their own platforms or focus on niche segments where they can combine deep sector expertise with embedded models?
For non-financial platforms, the decision to embed lending involves weighing potential revenue and loyalty benefits against regulatory exposure, operational complexity and reputational risk. Leaders must carefully select partners, define clear governance structures and ensure that credit offerings align with their brand values and customer expectations. As FinanceTechX continues to show in its global economy and banking coverage and banking analysis, the most successful embedded lending strategies tend to be those that are grounded in a deep understanding of customer needs, strong risk management and a long-term view of ecosystem development rather than short-term volume growth.
For policymakers and regulators, the rise of embedded lending underscores the importance of adaptive, technology-aware supervision that can balance innovation with stability and inclusion. Cross-border coordination, data standards and common principles for AI governance will be critical to ensuring that embedded finance contributes positively to economic development without creating hidden systemic risks.
What's an Embedded Future
As embedded lending continues to reshape business finance across the United States, Europe, Asia-Pacific, Africa and Latin America, FinanceTechX positions itself as a trusted guide for executives, founders, investors and policymakers seeking to navigate this complex landscape. Through its fresh reporting of fintech innovation, business strategy, global economic trends, jobs and skills, security, education and sustainability on its main platform, the publication aims to provide the depth of analysis, global perspective and practical insight that decision-makers require in an era where finance is increasingly invisible yet more deeply embedded than ever before.
Embedded lending is not simply a product trend; it is part of a broader re-architecture of financial services around data, platforms and ecosystems. Businesses that understand this shift, invest in the right capabilities and approach partnerships with a focus on transparency and long-term value will be best placed to harness its potential. Those that ignore it may find that the most critical financial decisions affecting their customers, suppliers and competitors are being made not in traditional banking halls, but deep inside the software platforms that now power the global economy.
